
Your Second Home Changed the Medicare Advantage Question.
By Lindsay Loomis, SVP of Growth, Emry Concierge
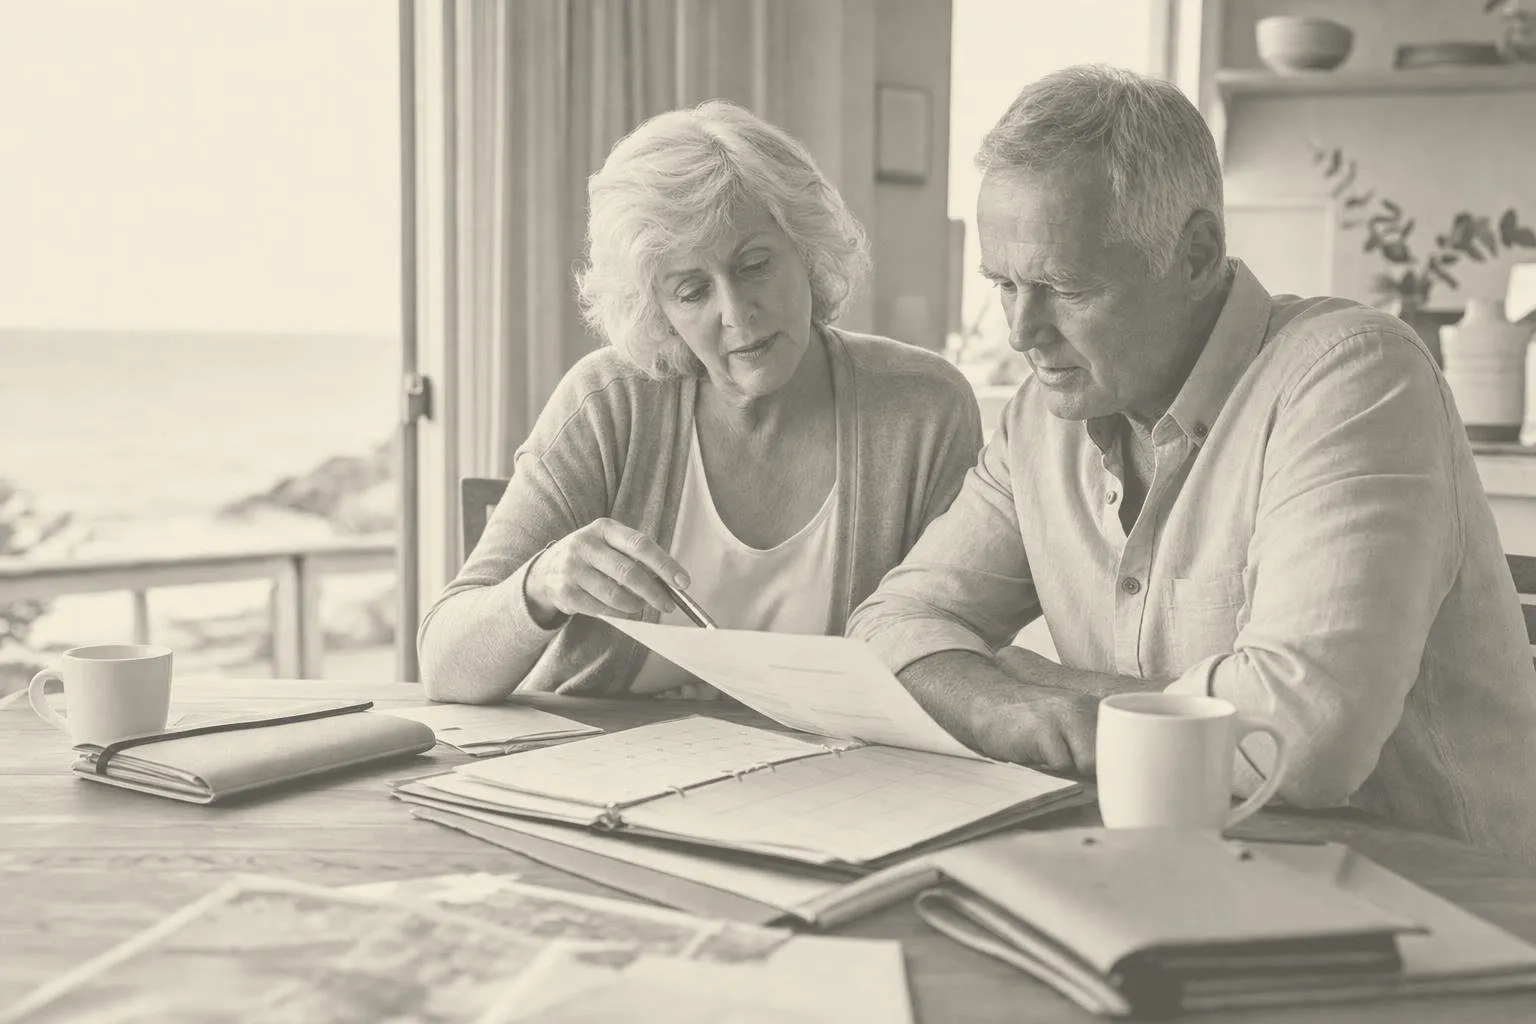
Consider a 68-year-old couple in Naples in late October, sorting through Medicare Advantage materials at the kitchen table before returning to New York for the holidays. One spouse has a cardiologist in Manhattan. The other expects to see an orthopedist in Florida this winter. The plan name looks familiar, and the premium looks reasonable.
For a Medicare Advantage second home situation, the question is whether the exact 2027 plan works across the exact doctors, hospitals, pharmacies and service areas that matter. The carrier name is only the beginning.
Why Medicare Advantage Second Home Coverage Needs a Network Check
Medicare Open Enrollment for 2027 coverage runs from Oct. 15, 2026, to Dec. 7, 2026, when people with Medicare can compare options through Medicare.gov, according to CMS guidance. For families who live in one place but receive care in two, that window is less a shopping season than a testing period.
The number of choices can make the work look deceptively simple. KFF found that the average Medicare beneficiary will have 28 Medicare Advantage prescription drug plan options for 2027, excluding employer plans and certain special needs plans, in its 2027 analysis. Choice, however, does not answer whether a winter physician, a summer hospital or a preferred academic medical center will take the exact plan.
That is where second homes change the Medicare Advantage review. A premium comparison may identify a plan that looks efficient on paper. A provider audit determines whether that plan can be used where care is likely to happen.
How Medicare Advantage Networks Work Across Two Homes
Under Medicare & You, Medicare Advantage plans may require members to use doctors and other providers in the plan’s network and service area for non-emergency care. A service area is the place a person must live for the plan to accept them. HMO rules are generally tighter, while PPO plans may allow out-of-network covered services at a higher cost if the provider agrees to treat the patient and has not opted out of Medicare.
This is the part families often miss. A PPO card in another state is not the same as guaranteed access to every specialist. Network participation needs to be confirmed by office, facility and plan. The useful question is not whether a carrier is familiar. It is whether this contract works at this address for this type of care.
A second home also creates a service-area record problem. Plans can, and in some cases must, disenroll someone who moves outside the service area. For families who split time, the residence on file and the expected care pattern need to be reconciled before a plan choice is made.
Original Medicare vs. Medicare Advantage for a Second Home
Original Medicare works differently for mobility. Beneficiaries can use any doctor or hospital that takes Medicare anywhere in the United States, including the 50 states, the District of Columbia and U.S. territories named by Medicare, according to Medicare & You.
But timing matters. A person who drops Medigap to join Medicare Advantage and later returns to Original Medicare may not be able to get the same Medigap policy back, or may pay more, depending on state enrollment rules and the person’s situation.
That makes the Original Medicare versus Medicare Advantage second home question more than a network preference. It is also a sequencing question, especially when retirement, relocation, a spouse’s needs or an aging parent’s needs may change care relationships.
What to Do Next
The work is a plan-by-plan audit before the enrollment window closes. Every must-have physician, facility, pharmacy and drug needs to be checked against the specific 2027 plan, not the carrier’s general reputation.
Medicare recently added searchable Medicare Advantage provider directories that allow up to five providers to be entered, including a must-have provider marker, according to KFF guidance. That tool is a starting point. The provider, location and plan still need to match.
County differences belong in the review as well. KFF found that Medicare Advantage prescription drug plan availability varies widely by county for 2027, with 193 counties having no such plans available for general enrollment, up from 123 in 2026, in its county review.
The second home is not the complication. The assumption that one network will follow the family everywhere is.
Frequently Asked Questions
Does Medicare Advantage Cover Care at a Second Home?
It may, but the answer depends on plan type, service area and provider participation near the second home. Routine non-emergency care is the harder category. Emergency and urgent care are treated differently, so the practical review has to focus on expected appointments, regular physicians, preferred facilities and prescriptions.
Can a Medicare Advantage PPO Be Used in Another State?
A Medicare Advantage PPO may allow covered out-of-network care, often at a higher cost. That does not create automatic access to every physician or hospital in another state. The provider still has to agree to treat the patient under that plan’s terms and must not have opted out of Medicare.
How Is Original Medicare Different for People With Two Homes?
Original Medicare generally offers broader geographic access because it can be used with providers that take Medicare across the United States. Medicare Advantage is more plan specific. For two-home households, the comparison turns on where routine care will occur, which doctors matter and how much future Medigap flexibility matters.
What Needs to Be Checked Before Choosing 2027 Coverage?
The review needs to match the specific plan against the family’s real use of care. That includes physicians, hospitals, pharmacies, regular prescriptions, out-of-network terms, service-area records and expected months in each location. Last year’s experience is helpful background, but it is not proof of next year’s access.
About Emry Concierge
Emry partners with advisory teams to ensure their clients’ healthcare infrastructure keeps pace with the transitions they help engineer. We handle the gaps, coverage and enrollment coordination, provider access, prescription continuity, claims, billing, and cross-policy complexity, so families aren’t left navigating the most personal parts of a major life change on their own. For advisors looking to offer a more complete service, we’re the piece that’s typically been missing.
Want to personalize this content for your clients? Create a free partner portal account to download, customize and co-brand this article.
Other case studies

Start your journey to simplified healthcare
Get connected with Emry Concierge today.